An insurance company is two offices in one building. At the front, underwriters, account managers and senior staff meet brokers, corporate clients and reinsurers in meeting rooms that have to look the part. At the back, claims handlers, customer service agents and medical pre-approval teams work in large, dense floors, often in shifts, with the pressure rising every renewal season. A pantry plan that serves only one of these halves fails the other.
This guide is for office managers, facilities leads and procurement teams at insurers, reinsurers, brokers, third-party administrators (TPAs) and insurtech firms in the UAE. It sits alongside our guides for banks and financial services, fintech companies and investment firms, which share much of the compliance context.
Where insurance firms sit in the UAE
Insurance in the UAE is regulated by the Central Bank of the UAE, with a large cluster of brokers, reinsurers and international carriers in DIFC and ADGM, national insurers headquartered in Abu Dhabi and along Sheikh Zayed Road, Business Bay and Downtown Dubai, and claims and service operations in lower-cost areas such as Dubai Silicon Oasis, Dubai Internet City and Al Reem Island. Many firms run both: a front office in a financial free zone and a back office elsewhere, which makes the pantry a multi-site programme from day one.
The front office: brokers, clients and reinsurers
Brokers are the insurer's customers as much as the policyholders are, and they visit often. The front office standard should be the same as a bank's:
- A reception offer of water, coffee, tea and Arabic coffee with dates, made within minutes. See the reception and visitor hospitality guide and the Arabic coffee and dates guide.
- Meeting rooms set to a written standard, with still and sparkling water, glasses and a small tray. The meeting room refreshments standard explains how to write one.
- A proper coffee machine near the client rooms. The coffee machine rental versus buying guide covers the choice for a firm that may grow or move.
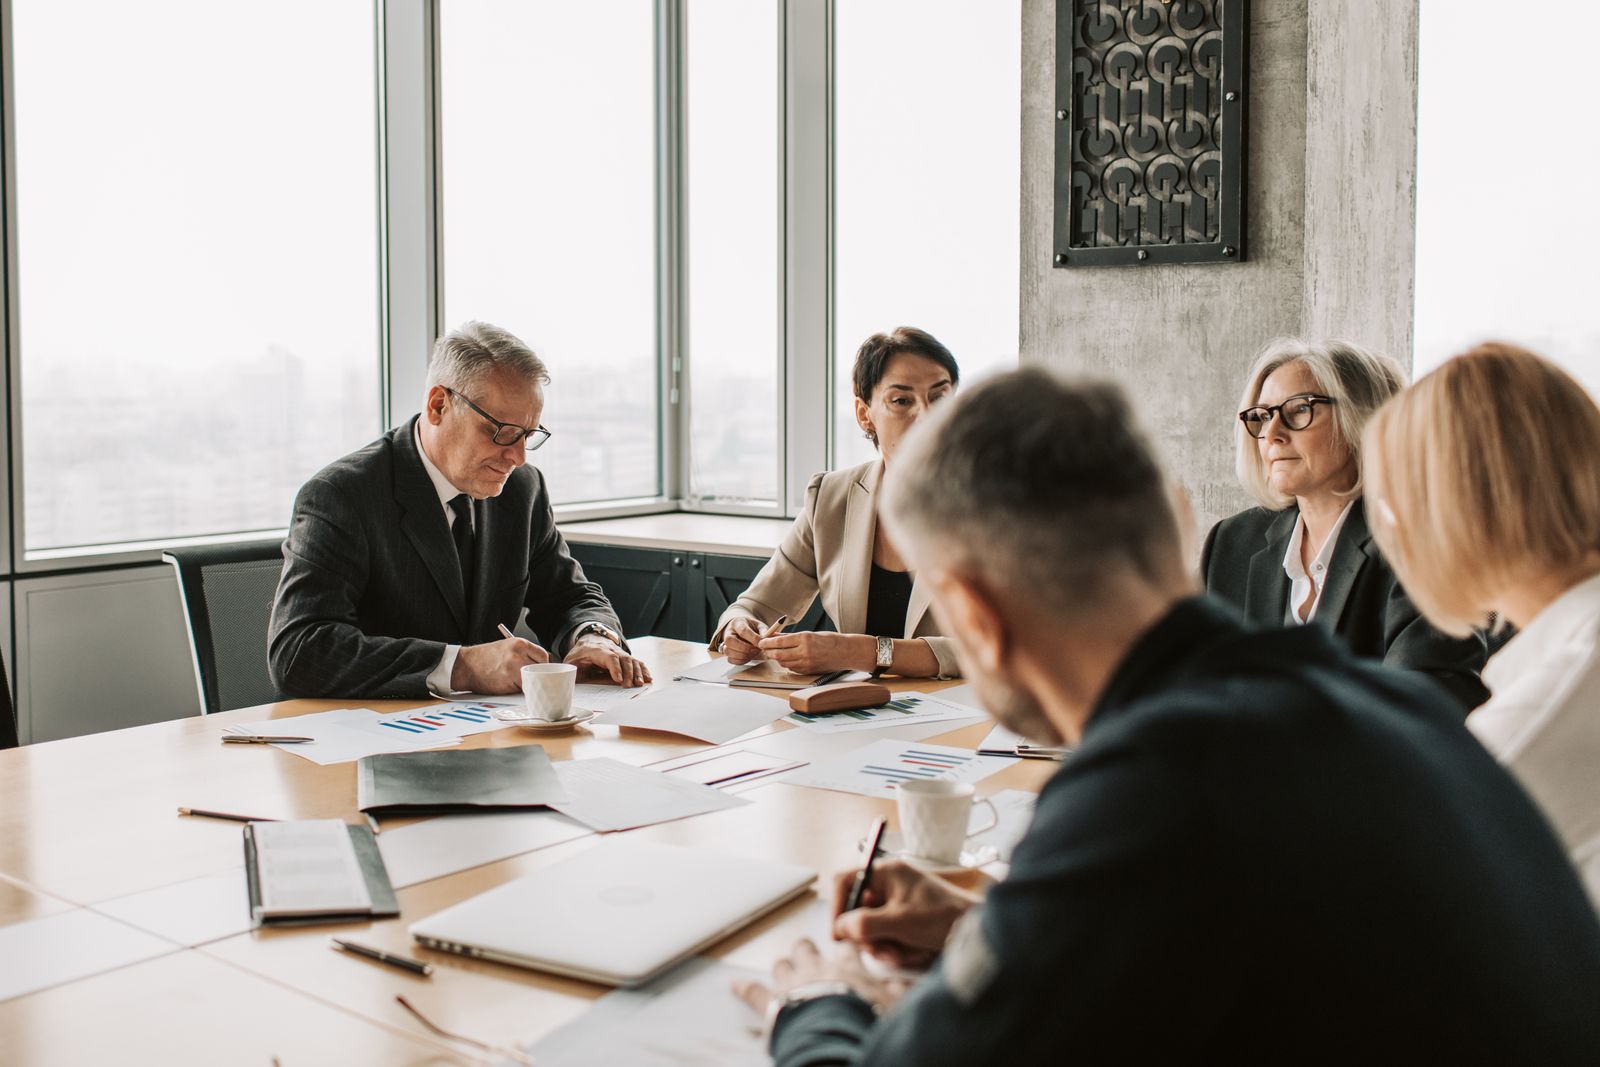
- Board and committee meetings catered quietly; see the board meeting and AGM catering guide.
The back office: claims, service and pre-approval floors
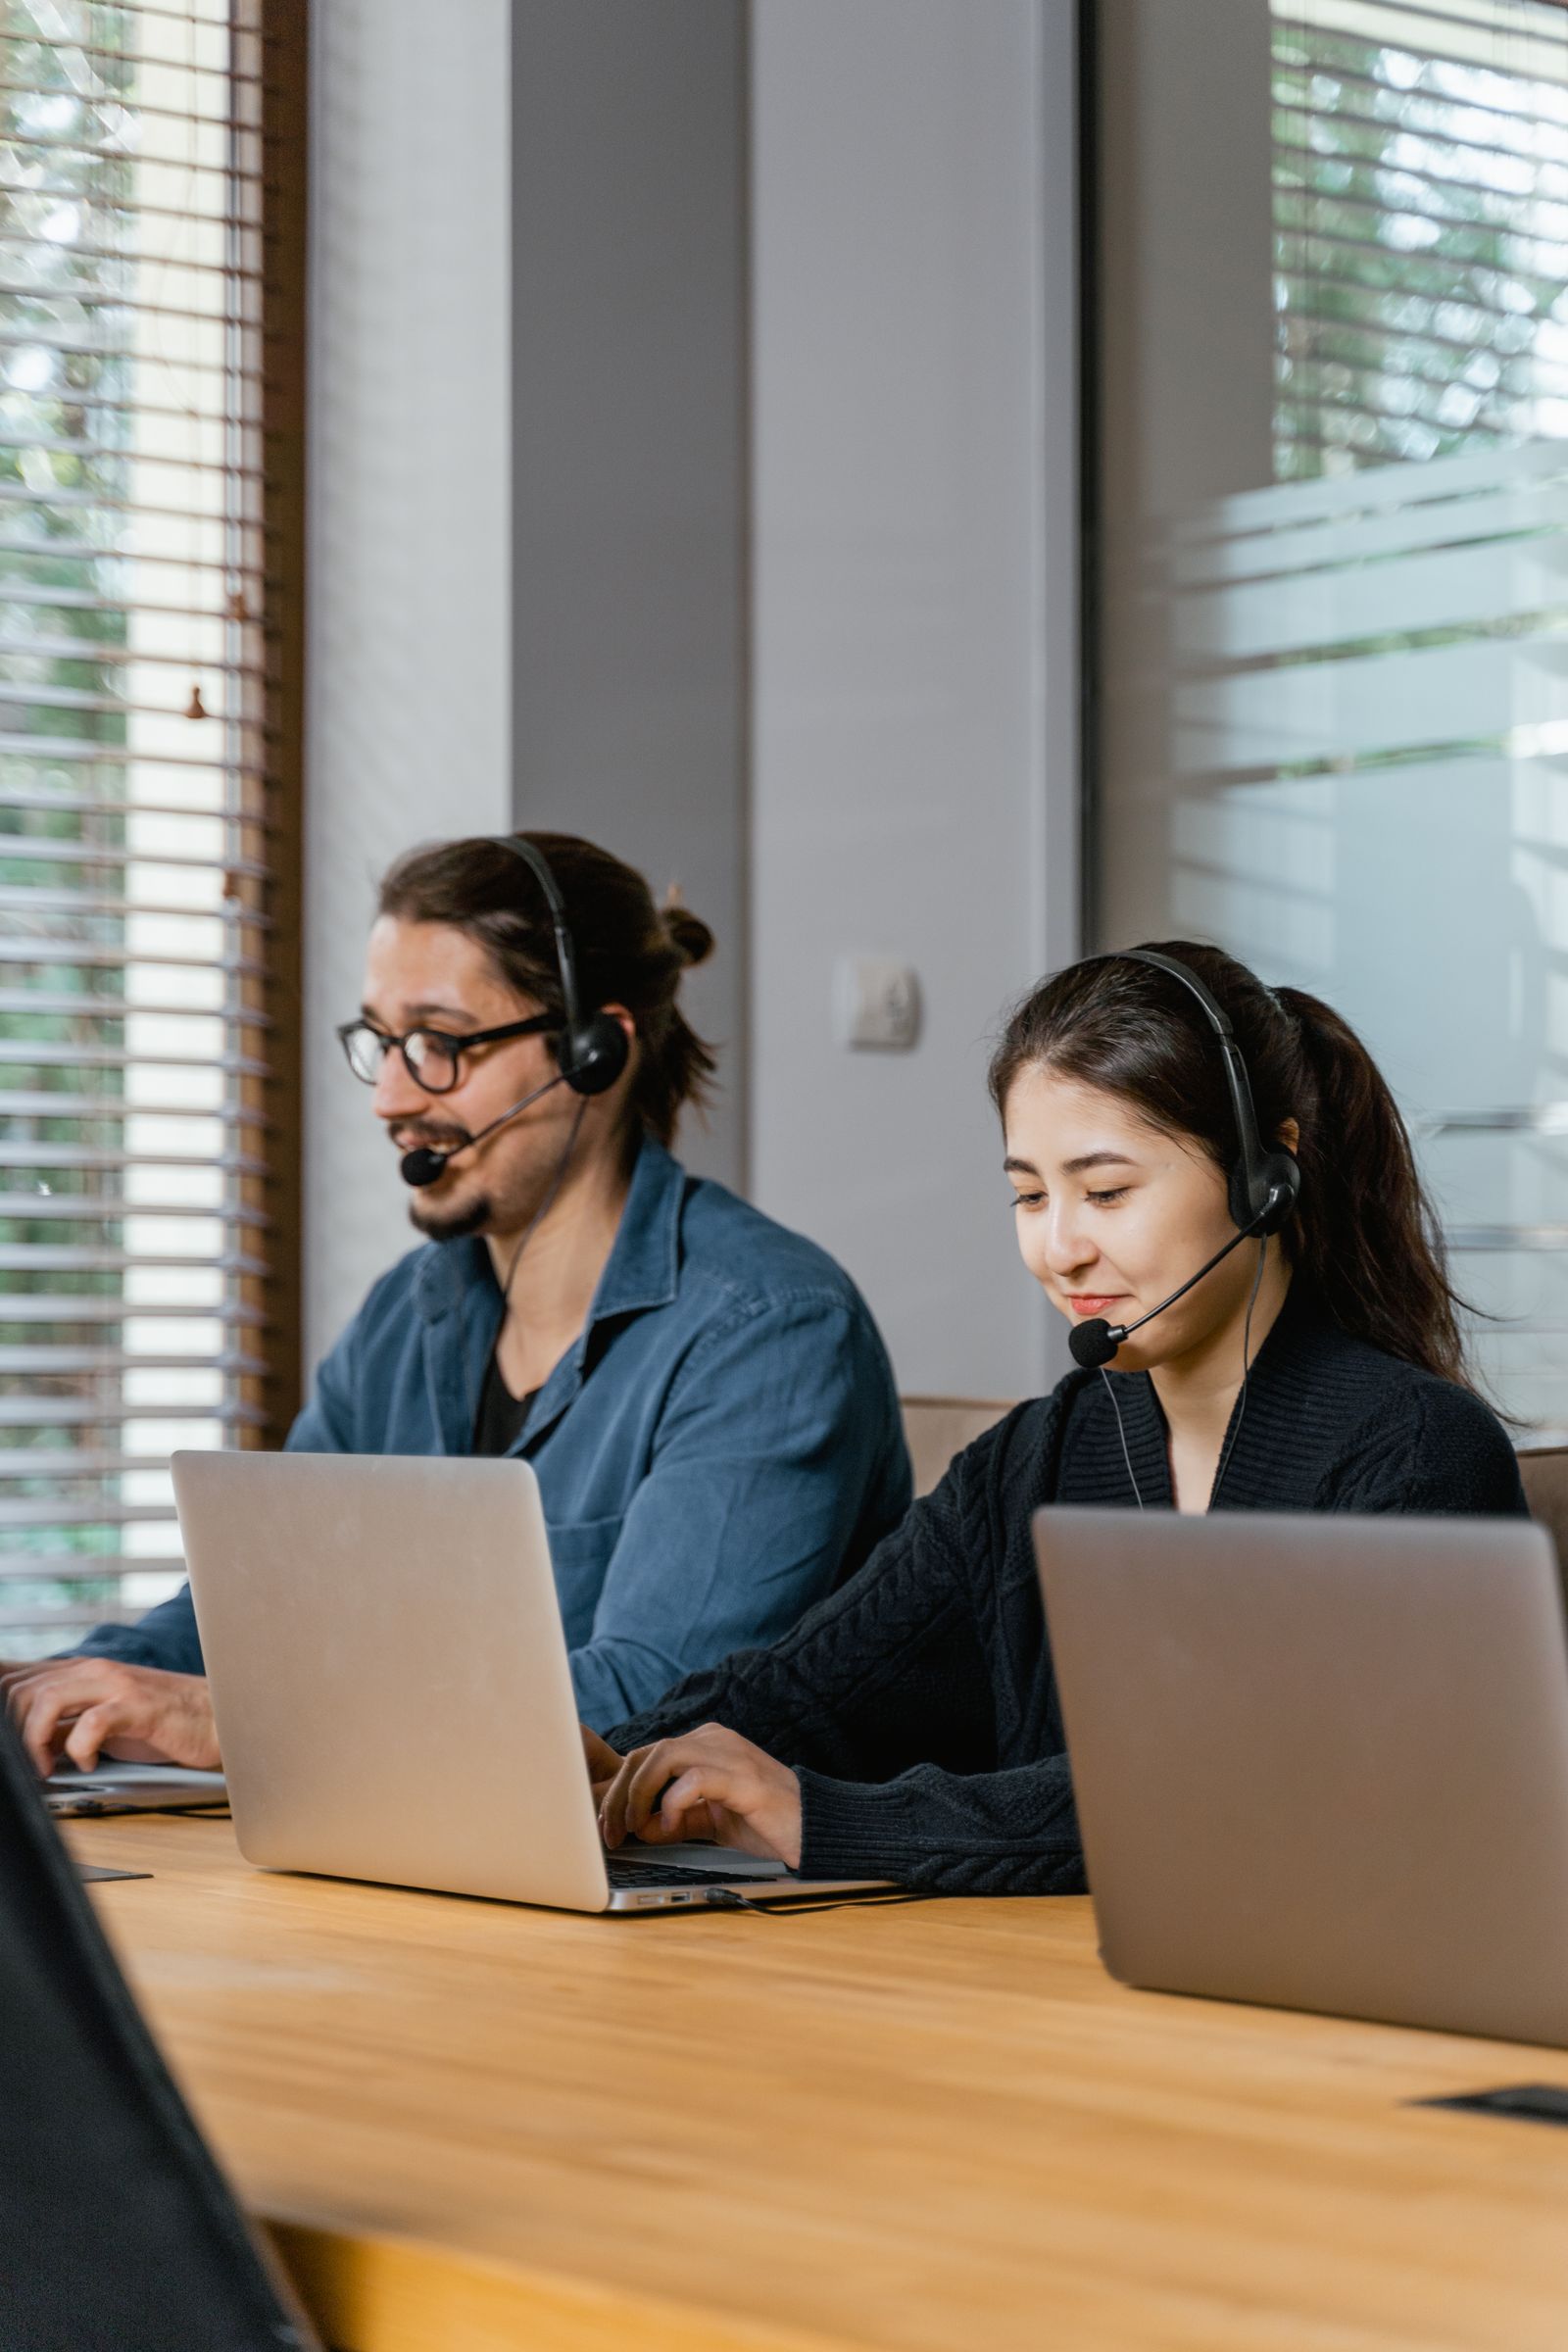
Claims and customer service teams in insurance work like a contact centre: timed breaks, headsets, evening and weekend coverage for motor claims and medical pre-approvals, and a lot of people in one room. Plan the pantry as you would for a service floor:
- Water dispensers on the floor, not only in the pantry, with juices and waters for variety.
- Fast coffee and a hot water point so a 15-minute break is not spent queuing.
- Warm, throat-friendly drinks: herbal teas and a decaf option for late shifts.
- Wrapped, desk-safe snacks: nuts and seeds, dried fruit and dates, low-sugar treats and office snacks in portion packs.
- Par levels per shift and a reserve for the evening team.
The call centre and customer service pantry guide goes into the detail, and the shift work guide covers overnight claims lines.
Renewal season and year-end
Insurance has peaks that the pantry should follow. Corporate renewals cluster around 1 January and 1 July, medical scheme renewals run through the fourth quarter, and the finance team closes the year under the same pressure as any other. In those weeks the underwriting and account teams stay late, the claims backlog grows and the office consumes well above its normal level.
Raise coffee, water and snack pars for the peak weeks, add a simple evening offer such as instant soups and ready meals and fruit, and plan the December wind-down with the Q4 pantry calendar and the year-end close guide for finance teams.
Compliance, procurement and paperwork
Insurers run supplier onboarding and invoicing to a standard that most pantry suppliers are not used to. Expect to be asked for a trade licence, VAT registration, insurance certificates, a signed code of conduct and, in a free zone, proof that the supplier can deliver into the building. The DIFC versus ADGM procurement guide sets out what the two zones require, the VAT guide explains recoverability on staff refreshments and client hospitality, and the payment terms and credit guide covers monthly invoicing on account. If the firm runs a formal tender, the RFP and tender template saves a week.
Budget
Treat the two halves separately. The front office runs at a hospitality-grade cost per head for a small number of people; the back office runs at a functional cost per head for many. The cost per employee benchmarks give ranges for both tiers, and consolidating the whole programme with one supplier under one catalogue keeps the front-office standard from leaking into the back-office bill. For a firm with several buildings, the multi-site playbook is the model.
Related sectors
Insurance shares its pantry profile with banks and financial services, fintech, family offices, law firms and healthcare for medical insurers and TPAs. See all the industries we serve and our delivery locations.
The short version
- Run the front office to a bank's hospitality standard and the claims floor to a contact centre's practical one.
- Set meeting rooms and reception to a written standard brokers will notice.
- Put water, fast coffee and wrapped snacks on the claims floor, with par levels per shift.
- Raise pars for renewal peaks in January, July and the fourth quarter.
- Choose a supplier that can pass insurance-grade onboarding and invoice cleanly on account.
Frequently Asked Questions
What should an insurance company's office pantry include? A hospitality standard for the front office, with water, coffee, tea, Arabic coffee and a snack tray for brokers and clients, and a practical standard for claims and service floors: water on the floor, fast coffee, warm drinks and wrapped snacks with par levels per shift.
How do we feed claims teams working evenings and weekends? Set par levels per shift, restock at the shift change, keep a reserve cupboard for the evening team and order from the roster rather than a fixed weekly quantity.
When are the busy periods for an insurance office pantry? Renewal peaks around 1 January and 1 July, medical scheme renewals through the fourth quarter and the year-end close in December and January. Raise coffee, water and snack pars for those weeks.
What documents will an insurer ask a pantry supplier for? Typically a trade licence, VAT registration certificate, insurance certificates, a signed supplier code of conduct and, in DIFC or ADGM, confirmation that deliveries can be made into the building.
Does My Healthy Office deliver to insurance offices in DIFC and ADGM? Yes. We deliver to DIFC, ADGM and office areas across Dubai and Abu Dhabi, supply the onboarding documents insurers usually require and invoice monthly on account.